
Zerodha, Groww and Upstox are all discount brokers that let you open a Demat account online and buy shares without visiting a branch. Zerodha leans towards traders and tools, Groww towards beginners and simple investing, and Upstox towards active traders who want speed and features. The better broker is the one that fits how you invest and what you actually pay, so check each broker’s current published charges before you open an account.
Which Is Better: Zerodha vs Groww vs Upstox?
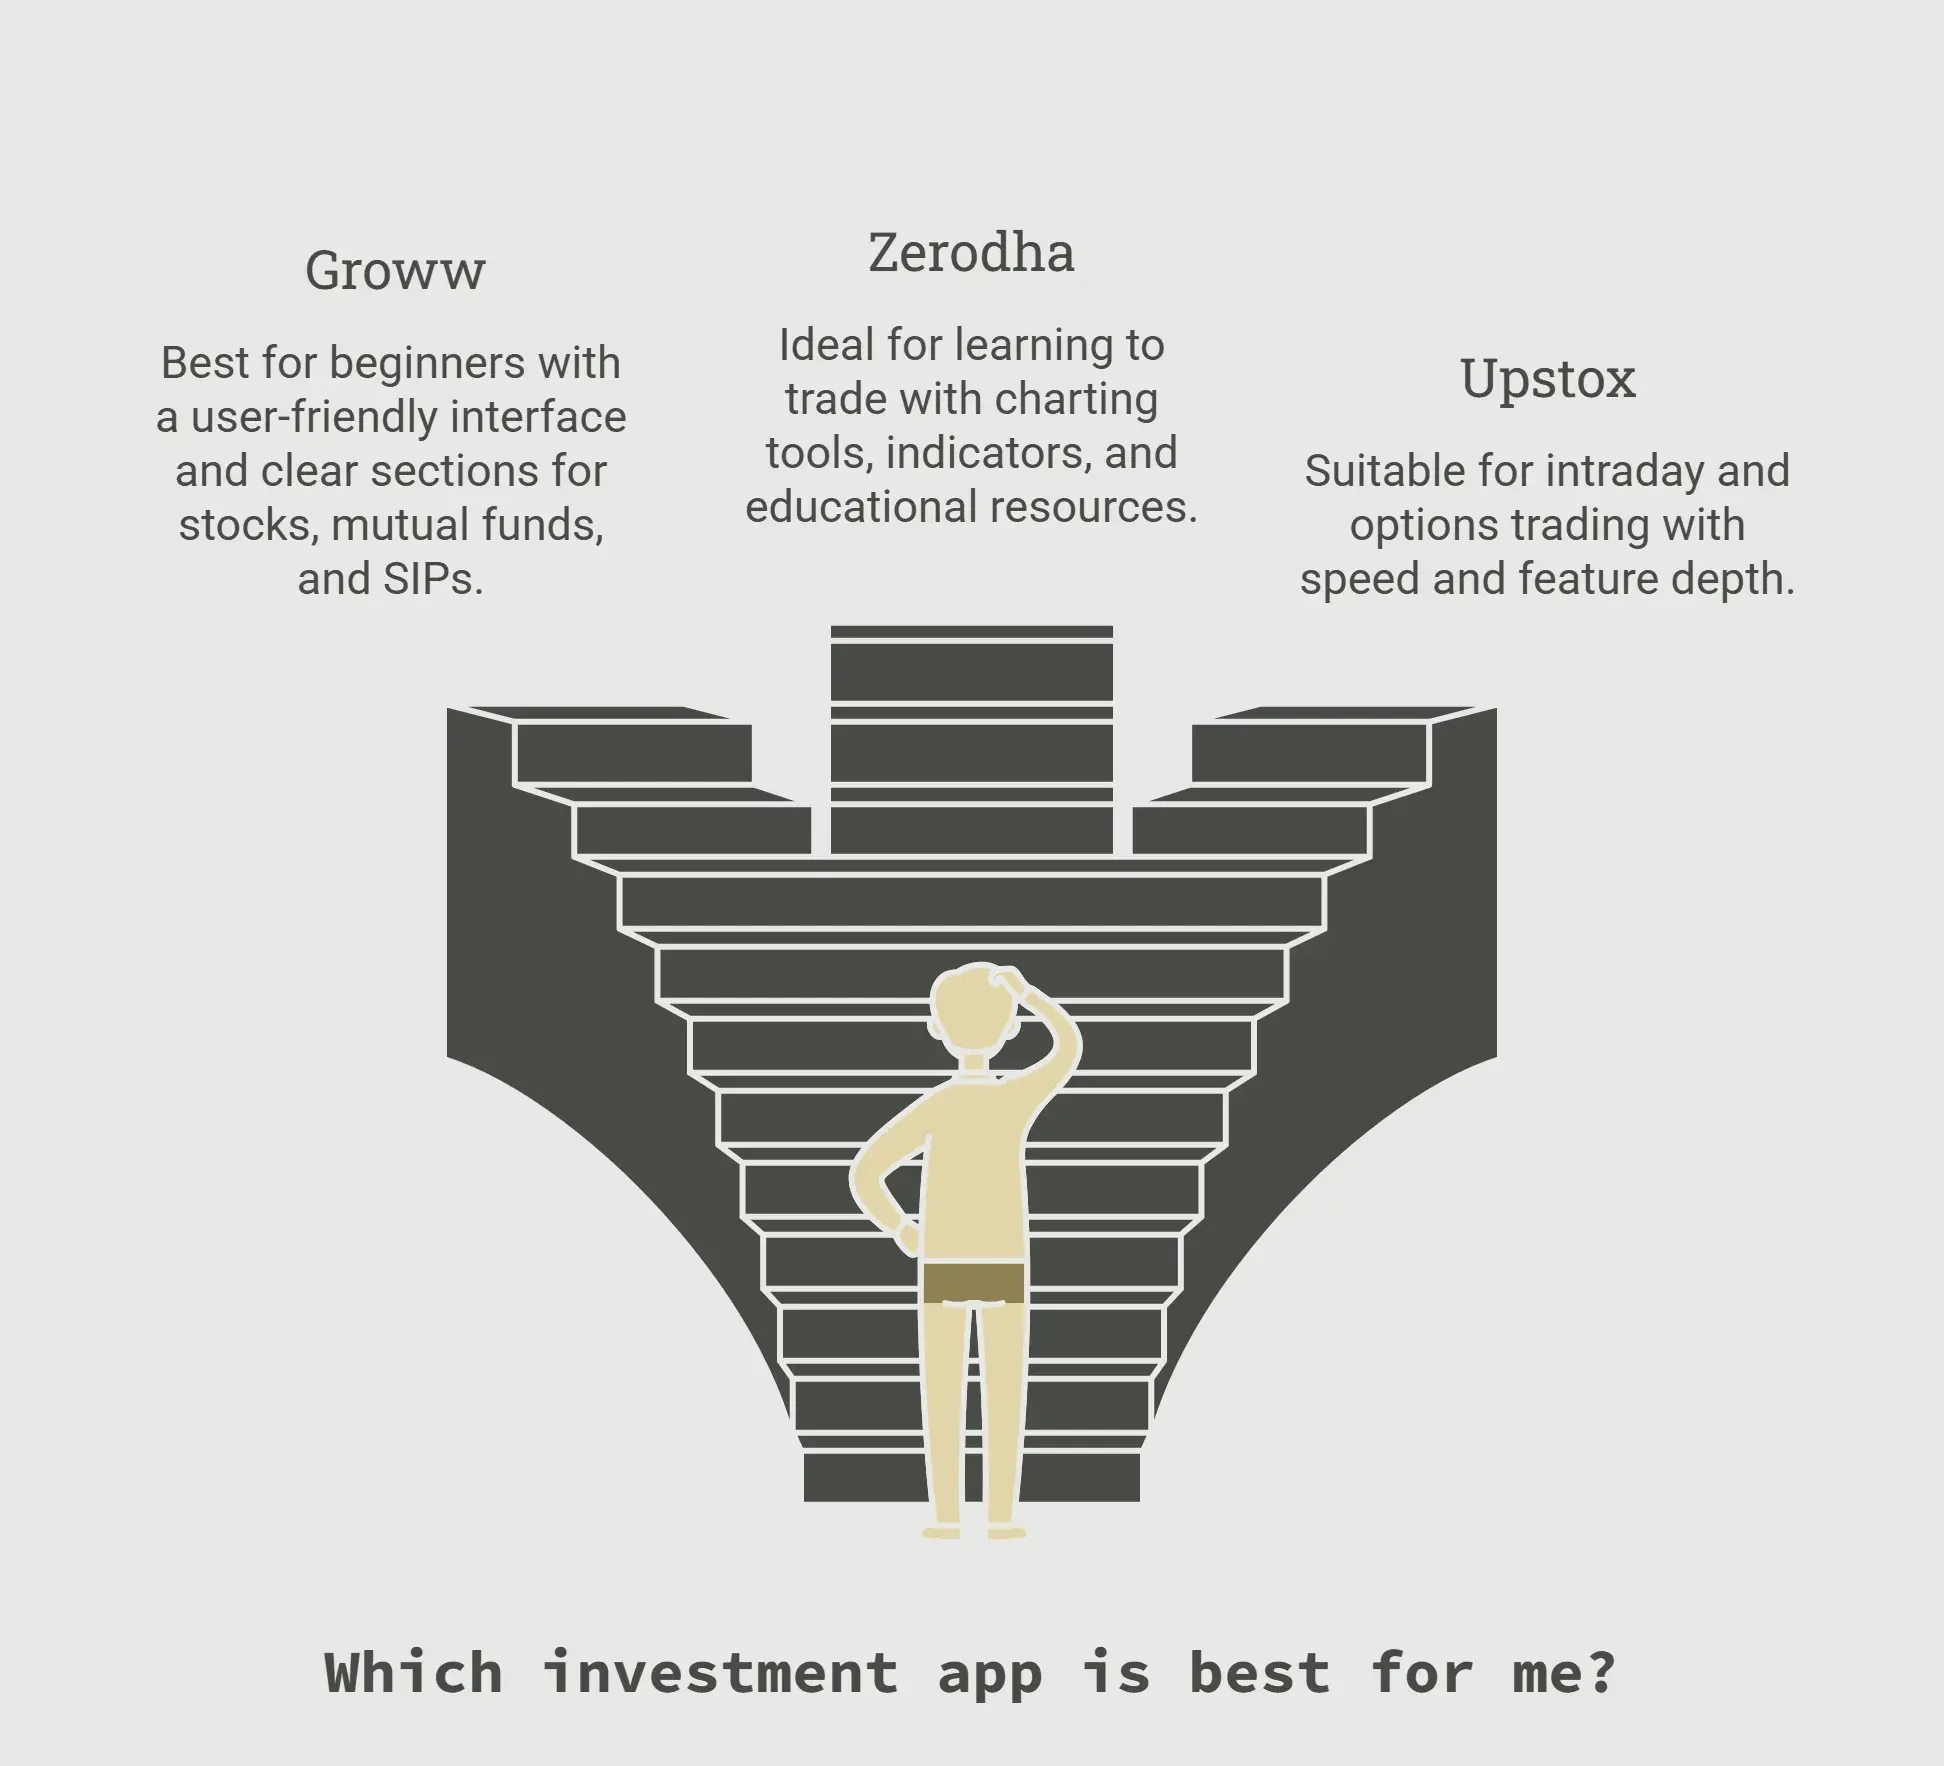
No single broker wins for everyone. Zerodha is often chosen by people who want to learn trading and use detailed charts. Groww is often chosen by first-time investors who want one simple app for stocks and mutual funds. Upstox is often chosen by active traders who want a feature-heavy platform for intraday and options trading.
All three describe themselves as low-cost discount brokers, and all three typically charge nothing for brokerage on equity delivery under standard plans. That means your decision usually rests on three things: the app you will be comfortable using at 9:15 in the morning, the fixed yearly costs, and the charges that apply to the way you trade.
| Point | Zerodha | Groww | Upstox |
|---|---|---|---|
| Known for | Kite trading platform and the Varsity learning material | Clean, minimal app that started with mutual funds | Pro platform with strong charts and multiple order types |
| Often suits | Learners moving towards trading, intraday and F&O users | First-time investors, SIP and ELSS users | Active intraday and options traders |
| Possible drawback | More tools can feel heavy for a complete beginner | Advanced traders may outgrow its tools | Feature depth can take time to learn |
| Mutual funds | Supported | Supported, a core strength | Supported |
| Where to check charges | Zerodha’s published pricing page | Groww’s published charges page | Upstox’s published pricing page |
Treat the table as a starting point, not a verdict. Features and plans change, so read each broker’s current charges page on the day you decide.
What Is a Discount Broker and How Is It Regulated?
A discount broker is a stockbroker that offers online buying and selling with limited or no advice, usually for a lower fee than a traditional full-service broker. You place orders yourself in an app, and the broker holds your trading account while your shares sit in a Demat account, which is the electronic locker for your securities. If you are new to this, how a Demat account works is worth reading first.
The securities market in India is regulated by the Securities and Exchange Board of India (SEBI). If a broker does not resolve a problem, SEBI runs a complaints system for investors, and its investor education portal explains your basic rights and how the market works. Reading it before you open any account is a sensible habit.
Opening an account needs KYC, which is identity and address verification. Brokers typically do this digitally with your Aadhaar, PAN and bank details. For a plain explanation of why this step exists, see why KYC is mandatory in India.
Who Is Cheaper: zerodha vs groww vs upstox?
For long-term investors who only buy and hold, brokerage on equity delivery is usually not the deciding cost, because all three describe zero brokerage on delivery under standard plans. For active traders, per-order brokerage, exchange charges and taxes add up faster and deserve a closer look.
The headline brokerage is only one line of what you pay. The table below lists the charges that commonly appear, who they affect most, and where to find them.
| Charge | Who it affects most | Where to check |
|---|---|---|
| Brokerage per order | Intraday and F&O traders | Broker’s pricing page and brokerage calculator |
| Demat annual maintenance charge (AMC) | Passive investors who trade rarely | Broker’s pricing page |
| DP charge on selling delivery shares | Anyone who sells shares from the Demat account | Broker’s pricing page |
| Exchange transaction charges, GST, SEBI charges | Everyone who trades | Contract note and broker’s calculator |
| Securities transaction tax (STT) | Everyone who trades | Contract note |
| Margin funding or MTF interest | Traders who use leverage | Broker’s margin and MTF terms |
| SMS, statement or off-market transfer fees | Occasional users on some plans | Broker’s pricing page |
Because plans and campaigns change, do not rely on a blog, a video or a friend for the current numbers. Open each broker’s own charges page and calculator, and run your own pattern through them.
How Much Do Charges Add Up to? A Worked Example
The example below uses made-up charges for two imaginary brokers, so you can see how the arithmetic works. These are illustrative figures only and are not the actual charges of zerodha vs groww vs upstox. GST, STT and exchange charges are left out to keep it simple.
Assume Broker A charges Rs 20 per executed order and Rs 300 a year as Demat AMC. Broker B charges Rs 0 per order for delivery trades, Rs 15 as a DP charge on each sale, and Rs 400 a year as AMC. Compare two investors for one year.
| Investor and pattern | Broker A (illustrative) | Broker B (illustrative) |
|---|---|---|
| Trader: 20 orders a month, 240 a year, no delivery sales | 240 x Rs 20 = Rs 4,800, plus Rs 300 AMC = Rs 5,100 | 240 x Rs 20 = Rs 4,800, plus Rs 400 AMC = Rs 5,200 (assuming it also charges Rs 20 on intraday orders) |
| Long-term investor: 3 buys and 2 sales a year | 3 buys and 2 sales at Rs 0 on delivery, plus Rs 300 AMC = Rs 300 | 2 sales x Rs 15 = Rs 30, plus Rs 400 AMC = Rs 430 |
Two points follow from the arithmetic. For the active trader, the Rs 100 gap in AMC (Rs 5,200 minus Rs 5,100) hardly matters next to Rs 4,800 in per-order charges, so the trading pattern drives the cost. For the long-term investor, the fixed AMC makes up almost the whole bill: all of the Rs 300 in one case and Rs 400 of the Rs 430 in the other. In real life you would also add taxes and exchange charges, which this example leaves out.
The lesson is to match the charge to your behaviour. A person who trades twice a year should look at AMC and DP charges first. A person who trades daily should look at per-order brokerage and exchange charges first.
Which App Is Best for Beginners, Traders and SIP Investors?
The best app is the one you can use calmly and correctly. A wrong order placed in a confusing screen can cost more than any brokerage difference, so test the app before you fund it.
Is Groww better for first-time investors?
Groww is widely seen as the most beginner-friendly of the three. Its app feels closer to a personal finance app than a trading terminal, with clear sections for stocks, mutual funds and SIPs. The trade-off is that someone who wants multi-timeframe screeners, complex watchlists or advanced option strategies may eventually find the tools limiting. If you are still learning how monthly investing works, SIPs explained with examples covers the basics.
Is Zerodha better for learning to trade?
Zerodha’s Kite platform is popular with Indian retail traders for its charting, indicators and multiple watchlists. Its Varsity learning material helps users understand ideas such as margin, options and risk. The trade-off is that more tools means more to learn, and access to tools does not make a trade profitable.
Is Upstox better for intraday and options?
Upstox sits between simple apps and heavy terminals. Its Pro platform offers charts, several order types and tools aimed at intraday strategies. Users who trade often value speed and feature depth, though more features can also make it easier to take bigger risks than you planned.
What About Outages and Platform Reliability?
Any broker’s app can slow down or fail during heavy volatility, and all three have faced occasional downtime or latency issues. For a long-term investor, a short glitch usually matters little as long as orders are eventually executed. For an intraday trader, an outage at market open can be costly.
Many investors keep a second broker account as a backup. This is allowed, and it adds a second set of charges to check, including a second yearly AMC.
Should You Invest While You Have Credit Card Debt?
This is a question about your own finances, and the answer depends on your numbers, so there is no single rule. What you can do is compare two costs honestly: the interest you pay on the card and the return you hope to earn from the market. Card interest is a certain cost that keeps adding up on an unpaid balance, while market returns are not guaranteed and can be negative.
Here is an illustrative case. Suppose you carry Rs 50,000 on a credit card at an assumed 40 percent a year, and you also want to invest Rs 5,000 a month. Over a year, interest on the Rs 50,000 would be about Rs 20,000 (Rs 50,000 x 40 percent), if the balance did not fall. A Rs 5,000 monthly investment totals Rs 60,000 over twelve months. For that investment to cover the Rs 20,000 interest cost alone, it would need to earn roughly a third of what you put in during the same year, which no market can promise. The 40 percent rate and the amounts are assumptions for illustration, so use your own statement.
The numbers will differ for each person, and some people reasonably keep a small SIP going while repaying debt. The useful step is to write down your card rate, your balance and your monthly surplus before deciding how to split money between repayment and investing.
If the card balance is the bigger worry right now, one option is to look at converting it into a structured EMI. See how BillCut works for credit card debt, and compare the cost against your current card interest before you decide.
Who Should and Should Not Choose Each Broker?
| Broker | May suit you if | May not suit you if |
|---|---|---|
| Zerodha | You want to learn trading step by step and value charting tools and reading material | You want the simplest possible app and never plan to trade actively |
| Groww | You are a first-time investor or mainly want stocks and mutual fund SIPs in one place | You expect advanced screeners and option strategy tools |
| Upstox | You trade intraday or options and want speed and several order types | You are a beginner who may be overwhelmed by many features |
You should probably wait before opening a trading account if you have no emergency savings, if you are borrowing money to trade, or if you are hoping a trade will clear a debt quickly. Trading carries risk of loss, and F&O trading in particular can lose money faster than most beginners expect.
How Do You Choose a Broker Step by Step?
- Write down how you will use the account: occasional delivery buying, SIPs, intraday or options.
- Shortlist two brokers and open each broker’s current charges page.
- Run one month of your expected trades through each broker’s own calculator.
- Open the account with the broker that looks better and place a few small delivery orders to test the app.
- Check your first contract notes line by line against what you expected to pay.
- Keep a second broker only if you will actually use it, since it brings another AMC.
Only download the official app from a trusted store and be careful with strangers offering tips or guaranteed returns. If you are targeted by a fake trading app or an investment scam, you can report it on the National Cyber Crime Reporting Portal. For broader consumer complaints against a service provider, the National Consumer Helpline is another route.
How Are Trading Profits Taxed?
Gains from shares and trading can be taxable, and the treatment depends on how long you hold, the type of instrument and whether the income is treated as capital gains or business income. Rates and rules change, so read the current guidance on the Income Tax Department website or speak to a qualified tax professional for your case. Your broker’s contract notes and annual statements will show the figures you need.
Payments to and from your broker usually run through your bank account, often by UPI. If you want to understand how those payments move, the basics of UPI explains the system, and NPCI is the body that runs it.
Frequently Asked Questions
-
Which broker is cheapest for long-term investment?
All three describe zero brokerage on equity delivery under standard plans, so long-term investors should compare Demat AMC, DP charges and other fixed fees on each broker’s current published charges page.
-
Are there hidden fees with Zerodha, Groww and Upstox?
Charges such as DP fees, exchange charges, GST, STT and statement or SMS fees can apply on top of brokerage. Read each broker’s current charges page and your contract notes.
-
Can I invest in mutual funds on Zerodha, Groww and Upstox?
Yes, all three support mutual funds. Groww is often seen as the most beginner-friendly for mutual funds, while Zerodha and Upstox offer broader trading tools.
-
Which broker is best for intraday and F&O trading?
Zerodha and Upstox are popular with intraday and F&O traders for their terminals and order types. Your discipline and risk control matter more than a small difference in brokerage.
-
Can I open accounts with more than one broker?
Yes, you can hold Demat and trading accounts with more than one broker, and many people keep a backup in case of outages. Each account may carry its own yearly maintenance charge.
-
Which is better for a beginner, Zerodha or Groww?
Groww is widely seen as simpler for first-time investors, while Zerodha suits beginners who want to learn trading with its tools and Varsity material. Test both apps with small delivery orders before you decide.
-
How do I check a broker’s current charges before opening an account?
Open the broker’s own pricing page and use its brokerage calculator with your expected monthly trades. Compare the result with your first contract note.
-
Does a Demat account have yearly charges even if I do not trade?
Many brokers charge a Demat annual maintenance fee whether you trade or not, and some waive it on certain plans. Check the current terms before you open the account.
-
Where can I complain if a broker does not resolve my problem?
Start with the broker’s own grievance process. If it is not resolved, SEBI runs a complaints system for investors, which is described on the SEBI website.
-
Should I invest in the stock market if I have credit card debt?
It depends on your card interest rate, your balance and your monthly surplus. Card interest is a certain cost, while market returns are not guaranteed, so compare both before deciding.
Are you still struggling with higher rate of interests on your credit card debts? Cut your bills with BillCut Today!