

By BillCut
Last Updated: October 2026
UPI, or Unified Payments Interface, is a real-time payment system created by the National Payments Corporation of India that lets you transfer money instantly using just your phone. Instead of entering long account numbers, you use a Virtual Payment Address (VPA), something like yourname@bank, and send money to anyone with a UPI account. Since its launch in 2016, UPI has grown to handle over 12 billion transactions, reshaping how Indians pay for everything from groceries to doctor visits.
How UPI Changed Payments in India and How does it Work?
UPI is a unified system that connects every bank in India through a single app on your phone. When you set up UPI, you link one or more bank accounts to a single Virtual Payment Address. This VPA is yours to keep, even if you change banks, you don’t share your account number or IFSC code with anyone.
Here’s what happens when you send money via UPI:
- You open your UPI app and enter the receiver’s VPA, phone number, or scan their QR code
- You enter the amount
- You authenticate using your UPI PIN (a 4-digit code you create)
- The money moves instantly from your account to theirs
The entire transaction takes about 10 seconds. There’s no waiting, no confirmation emails three days later. If the receiver is offline, they get the money the moment they come online. NPCI operates the backbone that makes this possible, a shared infrastructure that means your PhonePe app, Google Pay, Paytm, or your bank’s own UPI interface all talk to each other seamlessly.
UPI sits on top of the same real-time settlement rails used by NEFT, RTGS and IMPS transfers, but without any of the complexity. Those systems require you to know account numbers and bank codes. UPI abstract all that away.
Why UPI Was Needed in India
Before 2016, most digital payments in India were made through card networks, Visa, Mastercard, RuPay, or through digital wallets like Paytm that required you to pre-load money. Both had problems for India’s market.
Cards and wallet transfers were slow. Settlement happened the next day. Costs were high. A merchant paid 2-3% in fees to accept a card payment. For a person sending money to a friend, you had to own both a card and an internet connection, and both had to work.
Wallets required pre-loading, you had to transfer money in advance and keep a balance sitting there. If you needed to send Rs 5,000, you transferred Rs 5,000 into your wallet, then waited. This created friction. It also created a liability, stored value in a wallet was your responsibility if the wallet collapsed.
India’s payment system needed something simpler: direct bank-to-bank transfers, instant, with no pre-loading, no pre-payment, no stored value, no middleman holding your money. That was the insight that led to UPI.
The Growth of UPI in India
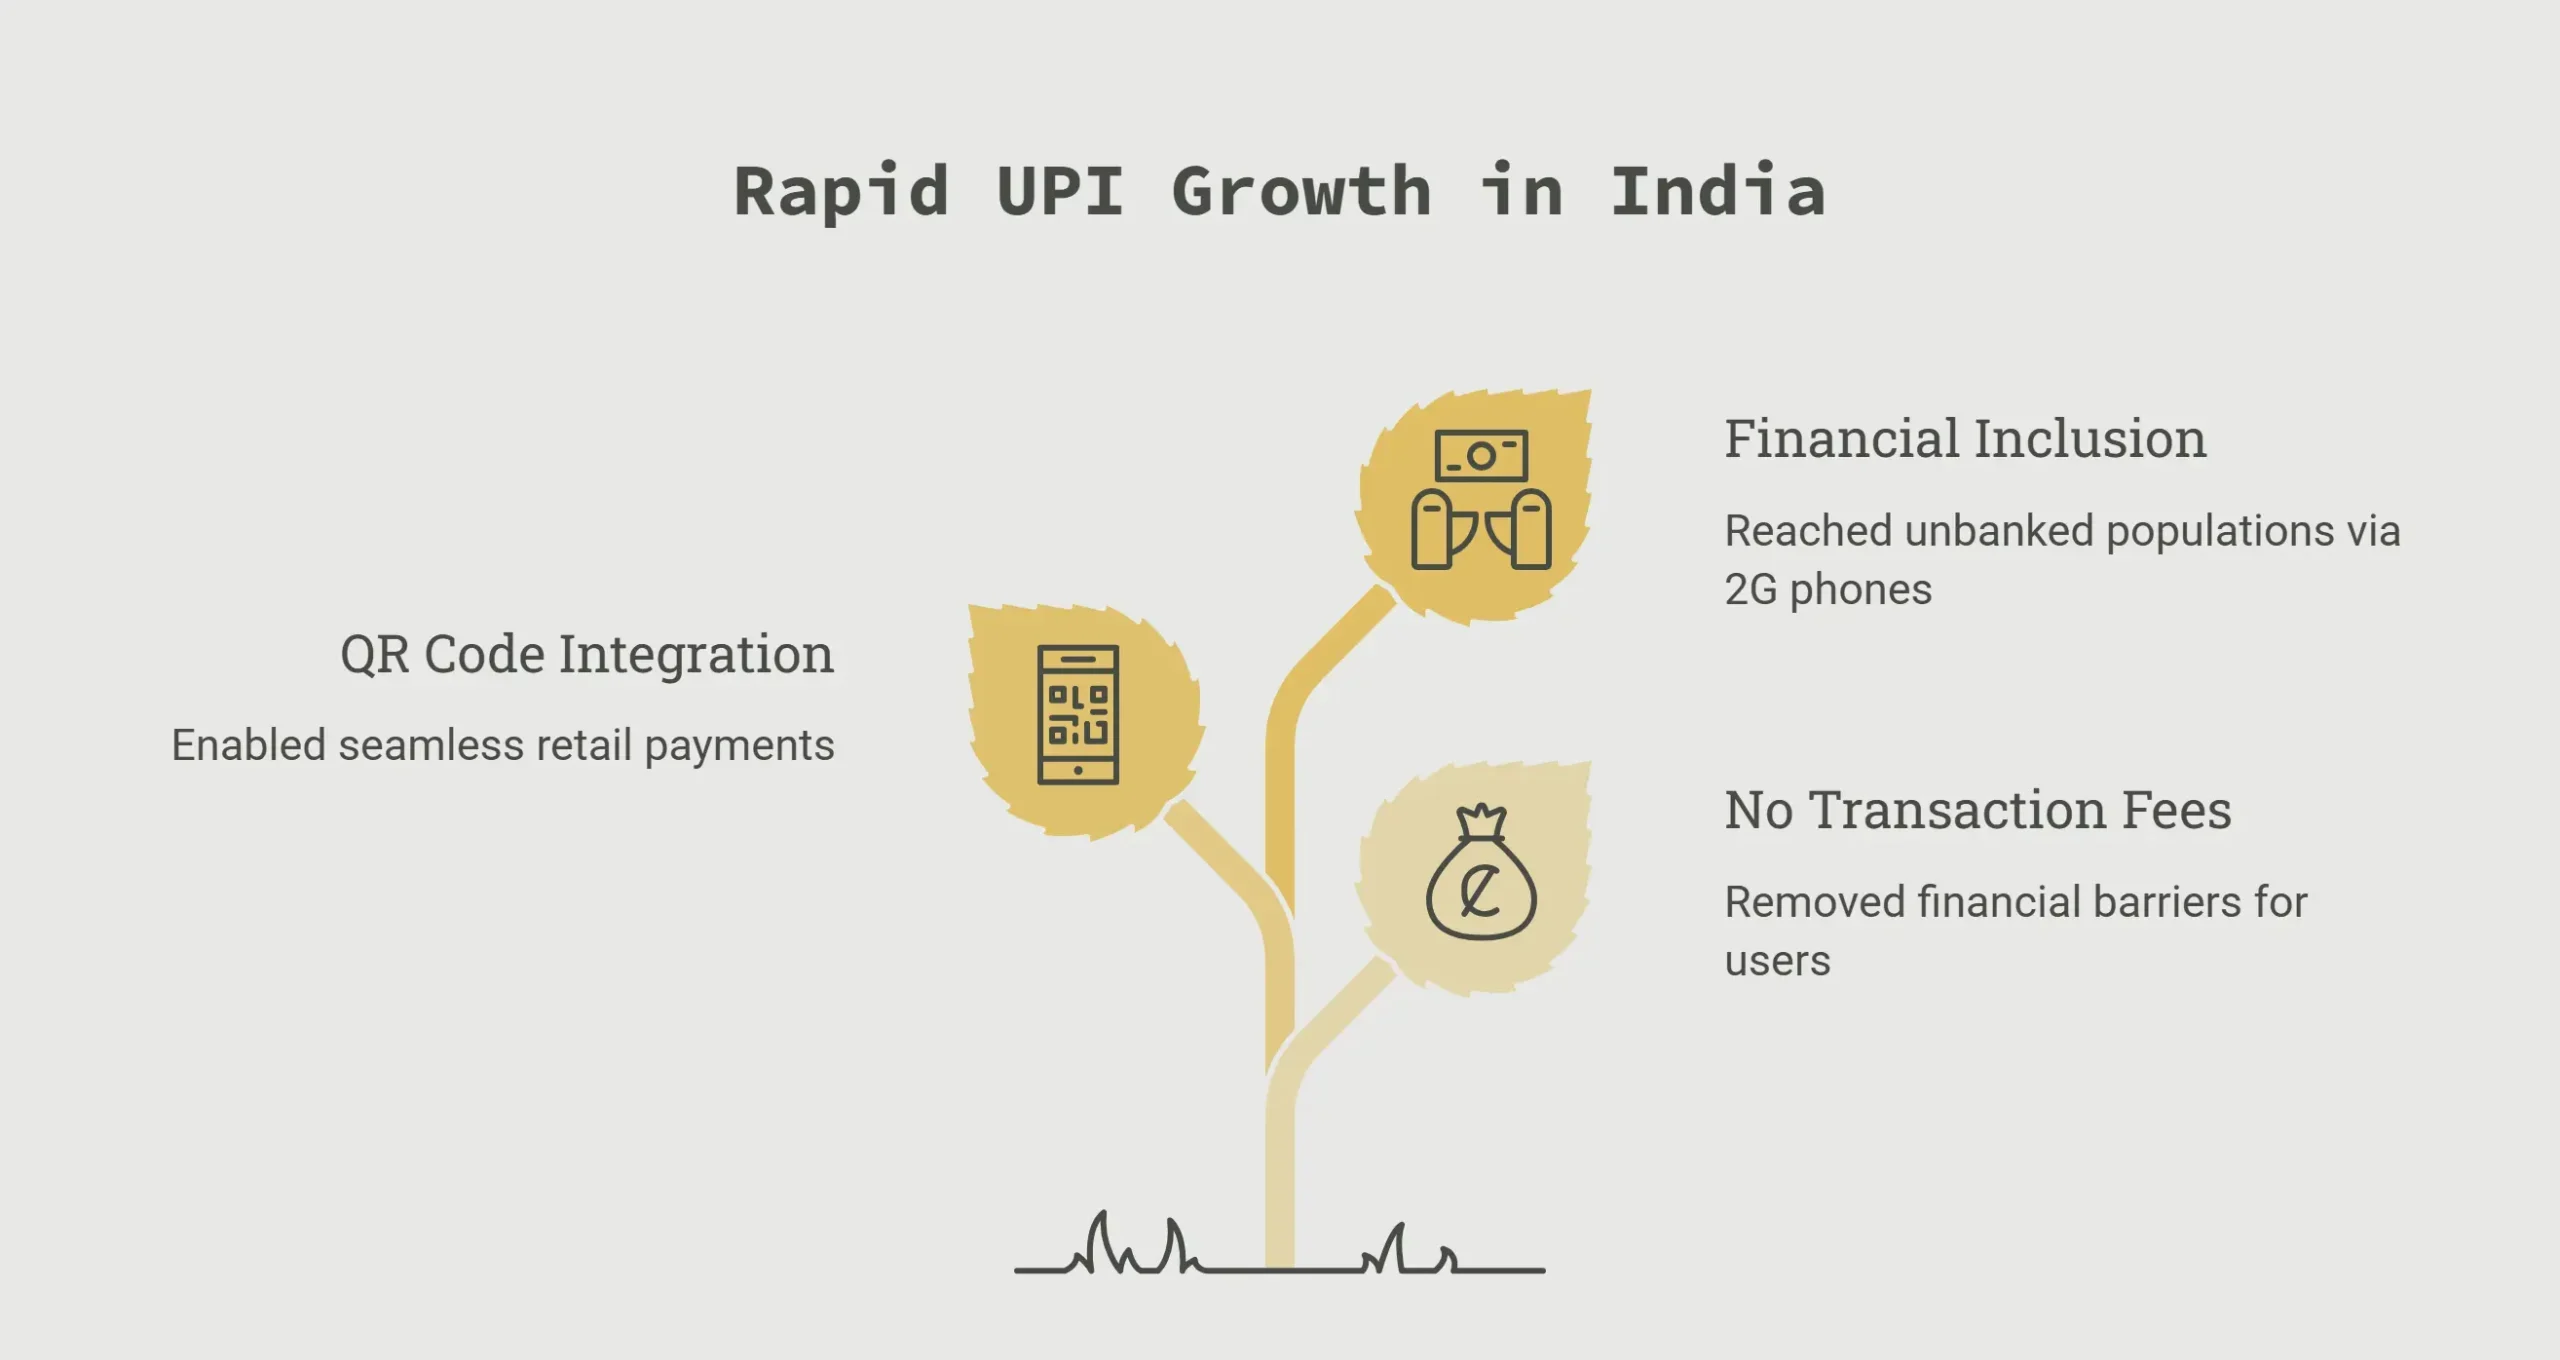
UPI’s growth has been extraordinary. In August 2024, UPI processed over 12 billion transactions, handling more volume than every other payment method in India combined. To put this in perspective:
This growth happened because UPI removed barriers. There’s no transaction fee for sending money. The friction is gone, you don’t need to pre-load. You don’t need a wallet. You send money from your actual bank account, which every adult in India has access to.
The second reason for growth was QR codes. Instead of sharing your VPA, a merchant prints a QR code on their receipt or till. You scan it, enter the amount, and the money goes straight to their account. This made UPI work for retail in a way digital wallets never did. Today, every vegetable vendor, auto driver, and tea shop in Indian cities accepts UPI via QR code.
The third reason was financial inclusion. UPI works on 2G phones. You don’t need a smartphone. You don’t need mobile data, you can initiate transfers over USSD (the old SMS-like protocol). This meant UPI could reach people in small towns and villages that had never had access to formal banking. Financial inclusion is no longer an abstract goal for India, it’s happening through UPI.
Key Benefits of UPI for Everyone
For consumers
Instant transfers: Money moves in seconds, not days. If your friend pays for dinner, you send their half back immediately.
No pre-loading: Your money stays in your bank account earning interest (however small). You don’t have to load it into a wallet ahead of time.
Direct bank connection: You’re not trusting an app with your money. You’re sending directly from your bank to someone else’s bank. NPCI operates the pipes, but your money never sits in anyone else’s account.
Works everywhere: The same UPI account works across every app, every bank, every merchant. You’re not locked into one wallet.
Small amounts, no fees: UPI was built for India’s payment patterns. People send money in small amounts, many times a day. There’s no charge.
For businesses and merchants
Lower costs: Traditional payment processing costs a merchant 2-3% per transaction. UPI costs them nothing. The government subsidised the infrastructure because it’s public goods.
Instant settlement: The money arrives in your account immediately. You don’t wait for payment processors to settle.
Larger addressable market: Because UPI is free and easy, more customers can pay. A vegetable vendor who can’t afford to pay card processing fees can accept UPI from thousands of customers who would otherwise pay cash.
Record keeping: Every UPI transaction creates a digital record. This builds credit history for small businesses and helps with tax compliance.
Less cash handling: Fewer notes and coins moving around reduces physical security risk and makes accounting easier.
UPI vs Other Payment Methods: A Comparison
If you have money to send and need to choose how, here’s what matters:
| Method | Speed | Cost | Ease | Who gets record | When funds arrive |
|---|---|---|---|---|---|
| UPI | 10 seconds | Free | Very easy | Both | Instant |
| IMPS | 30 minutes | Rs 5–25 | Complex | Both | Same day |
| NEFT | Next day | Rs 2–10 | Complex | Both | Next business day |
| Digital wallet | 10 seconds | Free | Easy | Wallet only | Instant to wallet |
| Cash | Immediate | Free | Easy | Neither | N/A |
For most people most of the time, UPI is simpler and faster than wallet-based transfers, and cheaper and instant compared to NEFT or IMPS. The only time you might use NEFT or IMPS is if you’re moving a very large amount and want the certainty that comes with a formal settlement system (which UPI also has, but through NPCI infrastructure).
How Secure Is UPI?
UPI transactions use two-factor authentication, your UPI PIN, which you never type out directly; and a one-time password sent to your phone when you set up a new payee. If someone steals your phone, they can’t use your UPI account without knowing your PIN. If they know your PIN, they still can’t access it without your phone.
Banks encrypt every transaction. The Reserve Bank of India and NPCI regulate the system. Every UPI app, whether it’s Google Pay, PhonePe, or your bank’s own app, must follow the same security rules. If a transaction is fraudulent, UPI transactions are reversible, and RBI guidelines require banks to refund you within 10 days.
That said, UPI fraud does happen. The biggest risk is not the system itself, but user error. If you share your UPI PIN, use public WiFi to log in, or fall for a payment reversal scam (where someone claims to have overpaid and asks you to send money back), you’re exposed. The technology is secure. Your behaviour around it is what you need to protect.
A Worked Example: How UPI Costs Compare
Let’s say you need to send Rs 50,000 to your sister for medical treatment, and you need to choose how.
Option 1: UPI
- Cost: Free
- Time: 10 seconds
- Record: Yes, you both have it
- Total time + cost: 10 seconds, Rs 0
Option 2: IMPS (Immediate Payment Service)
- Cost: Rs 25
- Time: 30 minutes
- Record: Yes, you both have it
- Total time + cost: 30 minutes, Rs 25
Option 3: NEFT (Net Electronic Funds Transfer)
- Cost: Rs 10
- Time: Next business day (can be up to 48 hours if initiated Friday evening)
- Record: Yes, you both have it
- Total time + cost: Up to 2 days, Rs 10
Option 4: Digital wallet to wallet
- Cost: Free
- Time: 10 seconds
- Record: Only the wallet provider has it; not tied to banking system
- Total time + cost: 10 seconds, Rs 0
UPI and wallet transfers are equally fast, but UPI ties to your actual bank account. If your sister needs a formal record for tax purposes or a bank loan, UPI is better than wallet-to-wallet. For most people, UPI is the obvious choice, it’s free, instant, and linked to your real money.
How UPI Has Changed India’s Financial Life
Five changes stand out.
1. Reduced cash in circulation. Before UPI, if you needed to give someone money urgently, you went to an ATM, withdrew cash, and handed it over. This created risk, took time, and meant no record. Today, people send money via UPI and close the loop in seconds.
2. Brought millions into formal banking. UPI works on a phone with almost no data. A person in a village can now accept payments directly into their bank account. For the first time, a street vendor or local shop owner can get a digital record of every sale. This builds credit history. It makes taxation possible. It brings the informal economy into view.
3. Ended the payment duopoly. Before UPI, you needed either a card or a digital wallet to make digital payments. Both required you to trust a company, Visa, Mastercard, or a wallet app, to hold your secrets and process your money. UPI broke this. Now, the government (via NPCI) runs the infrastructure, and hundreds of apps can plug into it. Banks compete for customers, but the customer doesn’t get locked in.
4. Made small businesses digital. A chai stall now accepts UPI because there’s no fee and no friction. This makes bookkeeping possible. It makes expansion possible. A small business that can see their daily sales digitally can plan. They can apply for loans.
5. Shaped how people think about money. UPI made digital payment the default. For people under 30, UPI is money. Cash is the exception. This changes behaviour. People send money constantly. They split bills digitally. They think of money as always accessible and always digital.
The Future of UPI
UPI is not finished evolving. Several developments are underway.
UPI Lite, launched in 2024, is a version of UPI for tiny transactions. It lets you store up to Rs 5,000 in a small wallet within your UPI account. You can transact without entering your PIN every time. This makes UPI even faster for daily purchases.
International expansion is happening. NPCI has launched UPI in Singapore and the UAE, with more countries planned. Indians sending remittances abroad may soon use UPI instead of expensive remittance networks.
Credit on UPI is emerging. Lenders are integrating with UPI to offer small loans that you can repay through UPI transfers. This turns UPI into a credit platform.
API Connections are bringing merchants directly onto UPI. E-commerce platforms and restaurants no longer need a separate payment gateway. They can integrate UPI directly.
Cross-border trade is being explored. If UPI can settle international payments, Indian small businesses selling to customers in Singapore or Sri Lanka could do so without needing an international payment processor.
The trend is clear: UPI is becoming not just a payment system, but a financial infrastructure layer. Everything from lending to insurance to investment could eventually move through UPI.
Who Should Use UPI and Who Might Need Alternatives
You should use UPI if:
- You need to send money instantly to another person
- You want to pay a merchant without carrying cash
- You need a record for tax or banking purposes
- You’re splitting an expense with friends or family
- You’re a small business accepting payments
You might need a traditional transfer if:
- You’re sending money internationally (for now)
- You’re sending very large amounts and need formal settlement certainty
- You need a printed statement for corporate accounting
- You’re sending to someone without a bank account
For most everyday payments, UPI is the right answer.
Debt Management and Digital Payments
For people managing credit card debt or loans, UPI changes the equation. When you receive salary, you can instantly transfer it to a loan account. When you pay multiple credit card bills, you can pay each one instantly, tracking exactly where your money goes. This visibility matters when you’re trying to reduce debt.
BillCut specializes in consolidating credit card debt into structured, lower-interest personal loans called debt refinancing. If you’re juggling multiple credit card bills with different due dates, interest rates, and payment methods, consolidating into one UPI-based EMI can simplify your finances significantly. You get one payment date, one interest rate, and total visibility into how much principal you’re paying down each month.
Frequently Asked Questions
-
What is UPI’s full form and what does it stand for?
UPI stands for Unified Payments Interface. It’s a real-time payment system created by NPCI that lets you transfer money using your phone, a Virtual Payment Address (VPA), and a 4-digit PIN.
-
Is UPI safe and secure for online transactions?
Yes. UPI uses two-factor authentication (your PIN plus a one-time password), encryption, and is regulated by RBI and NPCI. Fraudulent transactions are reversible and you’re refunded within 10 days under RBI guidelines.
-
How is UPI different from traditional digital wallets like Paytm or Google Pay wallets?
UPI transfers go directly from your bank account to someone else’s bank account. Digital wallets require you to pre-load money into the wallet first. UPI is faster, cheaper, and doesn’t lock your money in a wallet company’s account.
-
Can you use UPI for international payments or transfers abroad?
UPI is currently being piloted in Singapore and the UAE through NPCI’s international expansion. Broader international availability is planned, but for now, international transfers still require traditional remittance services.
-
How much money can you send via UPI in one transaction?
Most banks allow up to Rs 1 lakh per transaction, and up to Rs 1 lakh per day, though these limits vary by bank and the rules change periodically. Check with your bank for your specific limits.
-
What happens if you send money to the wrong UPI address by mistake?
UPI is designed to prevent this through a mandated payee authentication feature. When you add a new payee (VPA), the system shows you the payee’s registered name. If it doesn’t match, you’ll be warned before confirming. If you make an error, contact your bank immediately, reversals are possible within a few hours.
-
How does UPI support India’s financial inclusion and bring unbanked populations into formal banking?
UPI works on basic phones, requires no data (you can use USSD), and is free. This means a person in a remote village with just a basic phone and a bank account can send and receive money. They can now build a digital financial history.
-
Is there any transaction fee or charge for sending money through UPI?
No. UPI transfers between individuals are completely free. The government subsidized the infrastructure through NPCI to encourage adoption and financial inclusion. Merchants and businesses also pay no fees to accept UPI.
-
How does UPI handle foreign currency conversion if you receive international payments?
Currently, UPI operates only in Indian rupees within India. International UPI pilots in Singapore and UAE also use local currencies. Currency conversion would happen at your bank if you receive foreign currency transfers, and exchange rates apply.
-
Can you set up multiple UPI IDs or virtual payment addresses on the same bank account?
Yes. You can create multiple VPAs (like yourname@bank, yourname.1@bank) linked to the same account. This is useful if you want different VPAs for business and personal use, or for privacy.
This article is for information only. It is not financial advice and it does not recommend any UPI. Eligibility criteria, interest rates, fees and regulatory requirements change, and every figure in the worked examples is illustrative.
Are you still struggling with higher rate of interests on your credit card debts? Cut your bills with BillCut Today!