
By BillCut
Last Updated: October 2026
If you want to avoid overpaying on any loans in India, look past the monthly EMI. The total cost of a loan is driven by fees, the length of the tenure, the way interest is calculated, and the charges that apply when a payment is late or the loan is closed early. Most of these costs can be checked before you sign and reduced after you borrow.
What does overpaying on a loan actually mean?
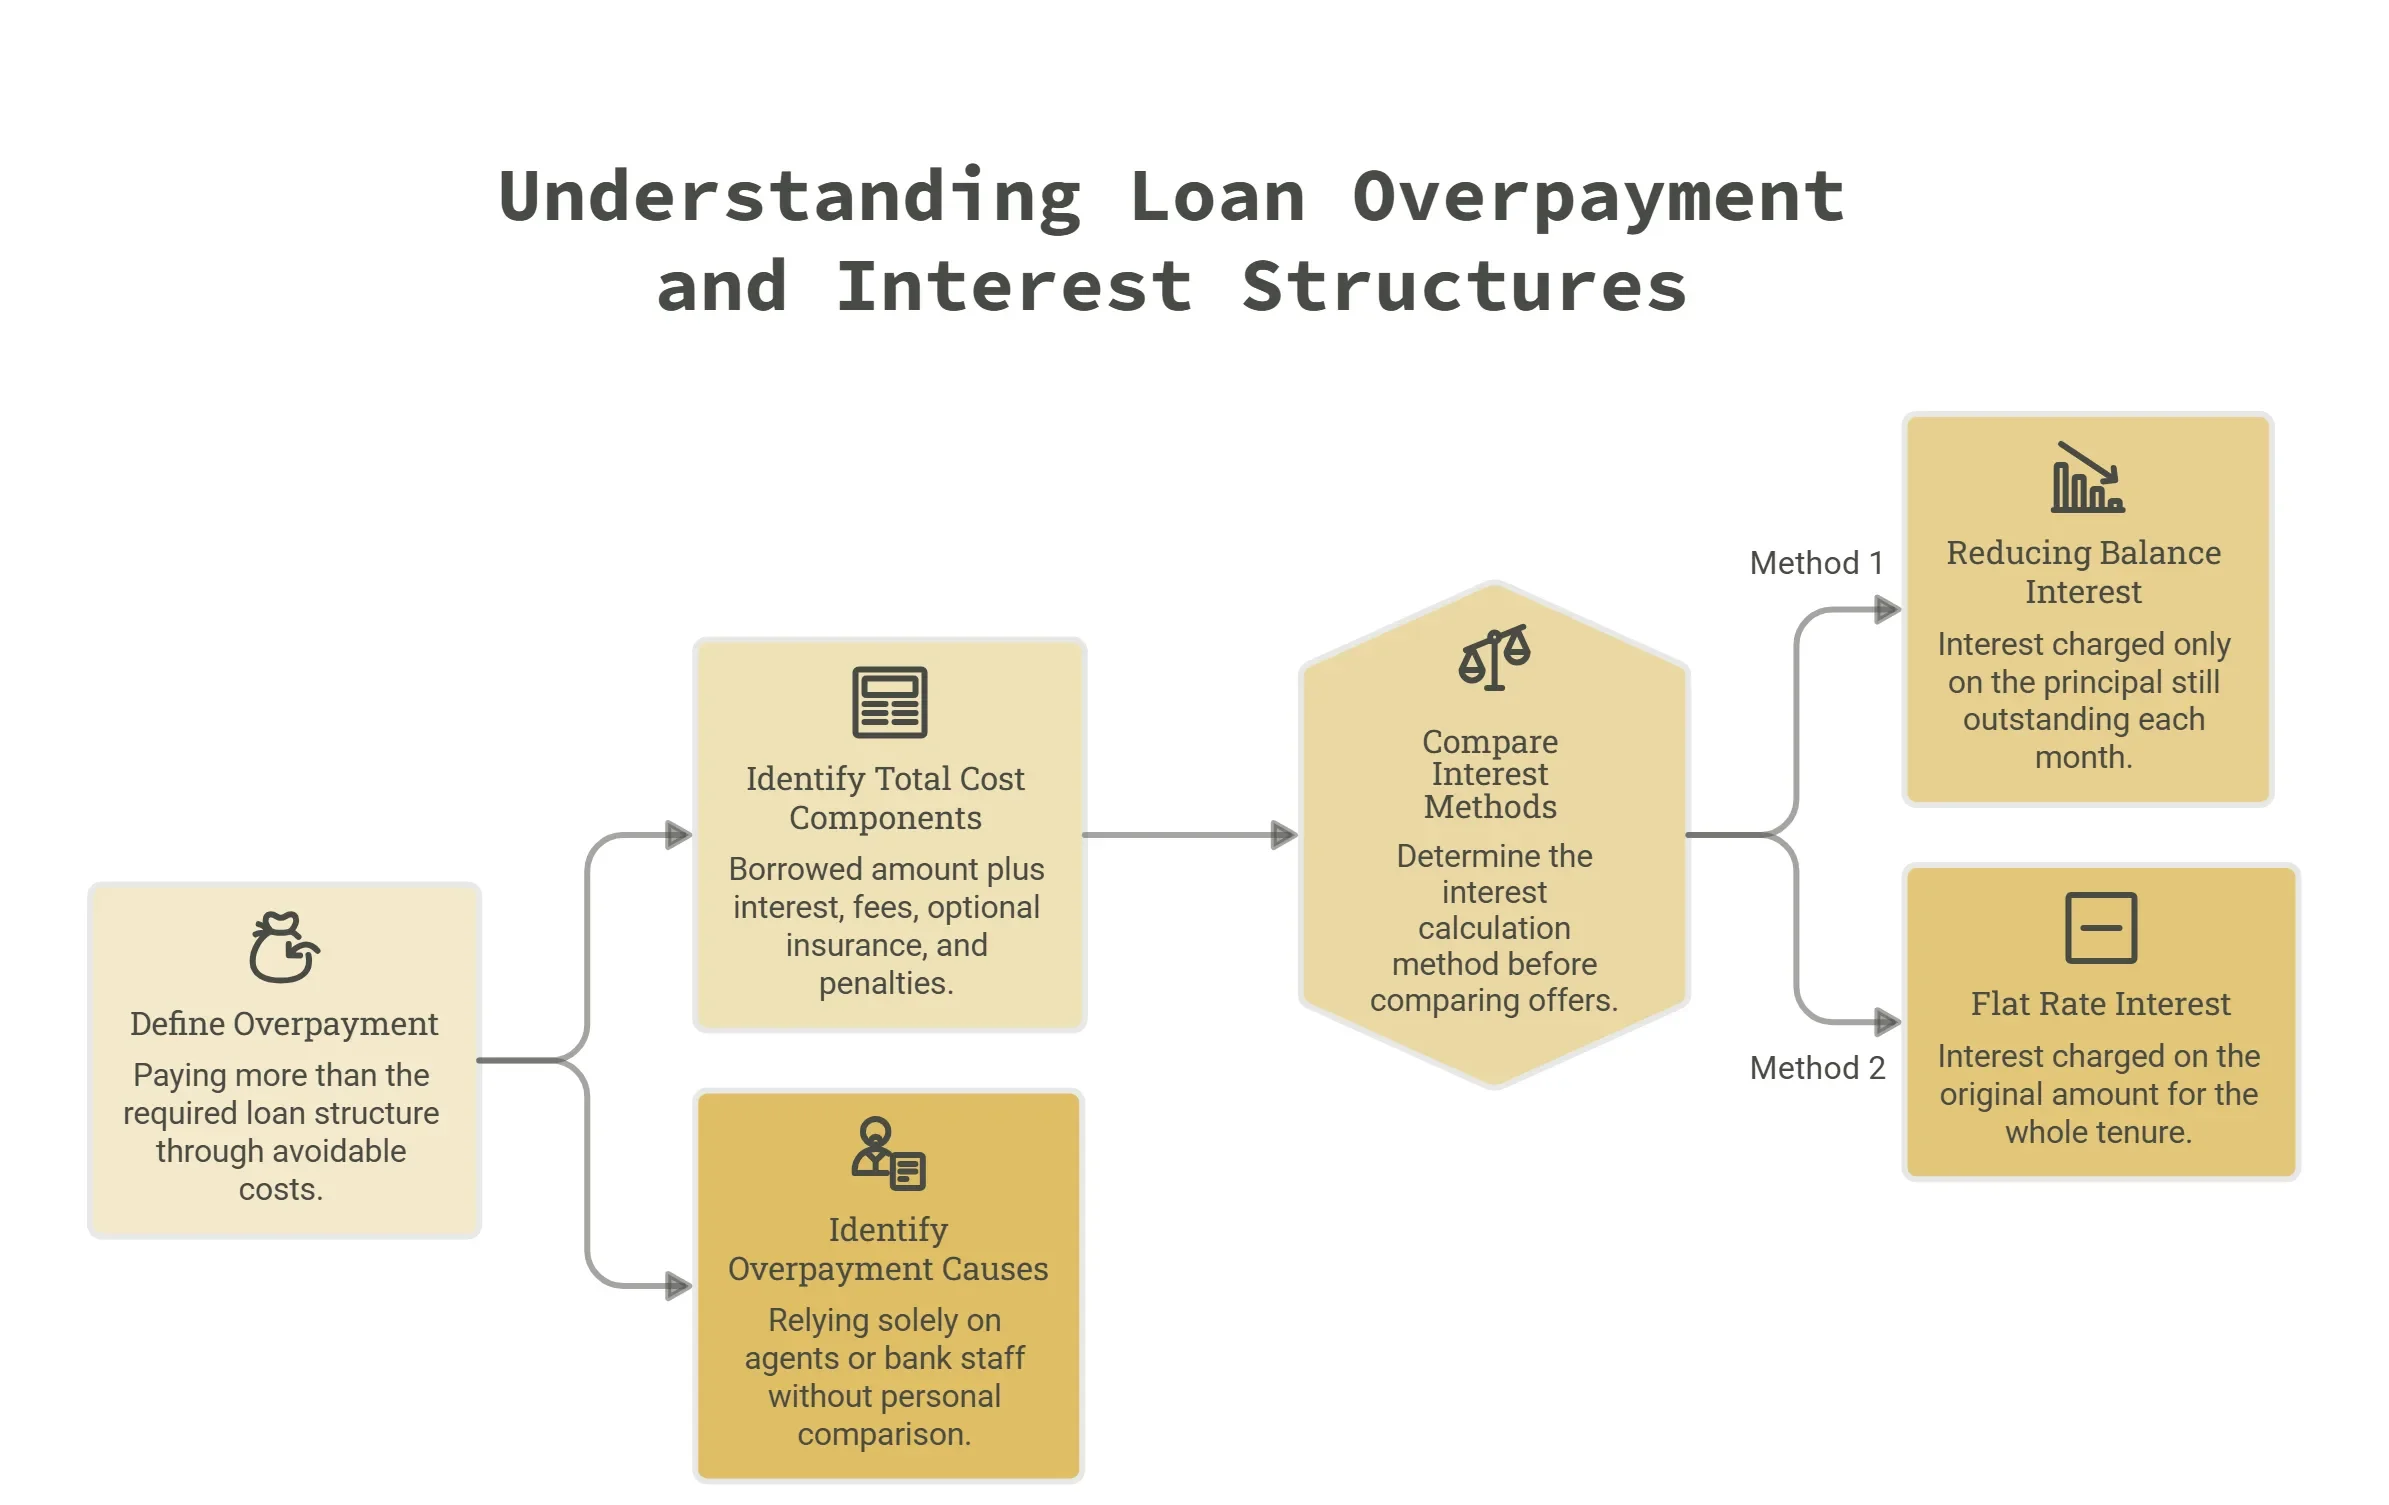
Overpaying on a loan means paying more in total than the loan structure required, through costs you could have seen or avoided. The equated monthly instalment (EMI) tells you the monthly outgo. It does not tell you the total cost, which is the amount you borrowed plus interest, fees, optional insurance, and any penalty added along the way.
Two terms matter before you compare offers. Reducing balance interest is charged only on the principal still outstanding each month. A flat rate charges interest on the original amount for the whole tenure, so its effective cost is higher than the headline rate suggests. Ask the lender which method applies to your loan before you compare.
Overpayment can happen when borrowers rely on an agent or bank staff member to explain a loan and do not compare offers themselves. A habit that does real damage is treating the EMI as the only number that matters.
What should you check on a loan offer before you sign?
| Item | What it does to your cost | Where to look |
|---|---|---|
| Interest calculation method | Decides whether interest falls as you repay (reducing balance) or stays on the original amount (flat rate) | Interest or rate section of the offer |
| Processing fee | Adds to your cost upfront and, when deducted from the loan, reduces the amount you receive | Fees section and schedule of charges |
| Optional insurance | Adds a premium that is paid only if you agree to the add-on | Optional products section of the loan agreement |
| Prepayment charge | Applies if you repay part of the loan before the end of the tenure | Schedule of charges and prepayment clause |
| Foreclosure charge | Applies if you close the whole loan before its end date | Schedule of charges and foreclosure clause |
| Late payment and bounce charges | Added on a missed or failed EMI, on top of the interest you already owe | Schedule of charges and default section |
For a digital loan, ask for the key fact statement before you accept. The Reserve Bank of India’s Digital Lending Directions, 2025 cover a key fact statement, a cooling off period and grievance redressal for digital loans. Compare that statement line by line with the offer you were shown, and treat any difference as a question for the lender in writing.
Lenders also differ in how they present the same loan. One lender may quote a low interest rate and a high processing fee, while another quotes a slightly higher rate with no upfront charge. The EMI alone cannot show you which is cheaper, so compare the total amount repayable across the full tenure.
What and how to avoid overpaying on any loans in India?
Each trap below adds cost quietly. The first two are set when you borrow, and the rest come from habits during repayment. Knowing them lets you spot the cost before it builds up.
Does a processing fee add to the cost of a loan?
Yes. A processing fee is charged upfront, so it adds to the cost before your first EMI is due. When it is deducted from the amount released to you, you receive less money but still repay EMIs on the full sanctioned amount. It is easy to focus on the interest rate and miss this fee, which is why it is worth comparing across lenders.
Illustrative example, with inputs chosen for arithmetic only: on a Rs 10,00,000 personal loan with a 2% processing fee, the fee is Rs 20,000 before any GST or other charges the lender adds. If the fee is deducted upfront, you receive Rs 9,80,000 but repay EMIs calculated on Rs 10,00,000. For more on this trap, read how to avoid overpaying on loan processing fees.
Does a longer tenure cost more in total?
Yes. A longer tenure lowers the EMI, but interest is charged for more months, so the total interest rises. The table uses the same illustrative loan of Rs 10,00,000 at an illustrative 12% a year on a reducing balance, for four tenures. These figures are computed from those inputs only and are not a lender’s offer or a current rate.
| Tenure | Monthly EMI | Total interest paid | Total amount repaid | Time to debt free |
|---|---|---|---|---|
| 3 years | Rs 33,214 | Rs 1,95,715 | Rs 11,95,715 | 36 months |
| 5 years | Rs 22,244 | Rs 3,34,667 | Rs 13,34,667 | 60 months |
| 7 years | Rs 17,653 | Rs 4,82,830 | Rs 14,82,830 | 84 months |
| 10 years | Rs 14,347 | Rs 7,21,651 | Rs 17,21,651 | 120 months |
Moving from five years to ten years in this example cuts the EMI from Rs 22,244 to Rs 14,347, a drop of about Rs 7,900 a month. Over the same period, total interest rises from Rs 3,34,667 to Rs 7,21,651, which is more than double. A lower EMI buys cash flow now at the price of a much larger total. If you are weighing several kinds of debt, the guide to personal loan traps Indians must avoid covers more examples of this pattern.
Why does most of the early EMI go towards interest?
Early EMIs pay mostly interest because interest is calculated on the balance still outstanding. In the first month of the illustrative 5-year loan, the Rs 22,244 EMI includes Rs 10,000 of interest and Rs 12,244 of principal. Each month the balance falls, so the interest share of each EMI falls too. The table shows the same loan year by year, computed from the same inputs.
| Year | Interest paid in the year | Principal repaid in the year | Balance at year end | Share of payments that is interest |
|---|---|---|---|---|
| Year 1 | Rs 1,11,643 | Rs 1,55,290 | Rs 8,44,710 | 41.8% |
| Year 2 | Rs 91,948 | Rs 1,74,985 | Rs 6,69,725 | 34.4% |
| Year 3 | Rs 69,756 | Rs 1,97,177 | Rs 4,72,547 | 26.1% |
| Year 4 | Rs 44,749 | Rs 2,22,184 | Rs 2,50,363 | 16.8% |
| Year 5 | Rs 16,570 | Rs 2,50,363 | Rs 0 | 6.2% |
This pattern is why the timing of any extra payment matters. The same rupee reduces the balance more when it is paid early, because more months of interest are avoided.
Do prepayments always reduce the cost of a loan?
A part-payment reduces the balance on which future interest is charged, so it usually lowers total interest. It does not always lower your cost, though. Some lenders apply a prepayment charge or a foreclosure charge, and the rule for your loan sits in the lender’s schedule of charges. Check it before you pay.
Illustrative example, using the same Rs 10,00,000 loan, 12% a year and 60-month tenure, with the EMI kept unchanged so the loan closes earlier: a Rs 1,00,000 part-payment in month 12 closes the loan in month 53 and reduces total interest by Rs 56,422, before any prepayment charge. The same part-payment in month 36 closes the loan in month 55 and reduces total interest by Rs 24,071. Both figures assume no charge applies.
| Scenario | Months to close | Total interest paid | Interest saved before any prepayment charge |
|---|---|---|---|
| No part-payment | 60 | Rs 3,34,667 | Rs 0 |
| Rs 1,00,000 part-payment in month 12 | 53 | Rs 2,78,245 | Rs 56,422 |
| Rs 1,00,000 part-payment in month 36 | 55 | Rs 3,10,596 | Rs 24,071 |
If the charge on your loan is higher than the interest you would save, a part-payment can cost you more than it returns. Compare the two figures before you decide.
What happens if you pay only the minimum due on a credit card?
Paying the minimum amount due keeps the account current for that billing cycle, but it leaves the rest of the balance to carry interest. Your card issuer’s terms set when interest starts and how it is charged, so read the statement and the terms for your card. The Reserve Bank of India sets billing and statement rules for cards in its Master Direction on Credit Card and Debit Card Issuance and Conduct, 2022, as updated in March 2024.
The unpaid balance keeps carrying interest until it is cleared. The minimum amount is therefore the least you can pay, not the amount that saves you money. Where you can, pay the full statement balance, and treat the minimum as a floor rather than a target.
Do missed EMIs and bounce charges add to the cost?
Yes. A missed or failed EMI can attract late payment charges and bounce charges on top of the interest you already owe. The Reserve Bank of India’s rule on penal charges in loan accounts requires a penalty to be a flat penal charge that cannot be compounded into interest. A penalty therefore does not grow into interest on itself, but it still adds to what you pay.
A single missed date can start a cycle of charges and catch-up payments, which is how small delays become expensive. The guide on why Indians delay paying loans and what the impact is explains how that cycle builds. Set EMI reminders for the day before the due date, and keep a small buffer in the account that pays the EMI.
Does renewing or rolling over a loan add to the cost?
It can. Some lenders charge a fee each time a loan is renewed or rolled over, and that fee can come back every time. Illustrative example, not a lender’s terms: on a Rs 10,000 loan with a Rs 300 fee charged on each renewal, three renewals cost Rs 900 in fees alone, before any interest. Ask whether a renewal triggers a new fee, and how much that fee is, before you agree.
What is loan stacking and why does it cost more?
Loan stacking means holding several loans at once, often from different lenders, to cover the same shortfall. Each loan brings its own processing fee, its own EMI and its own charges for late payment. The combined EMIs can leave little room for an emergency, which makes a missed payment more likely. The guide to hidden loan charges Indians often miss lists the charges to look for across each loan.
Before you take another loan, add up the EMIs and the recurring charges across all the loans you already have. If the total leaves no room for a month with lower income, the new loan adds risk rather than solving the problem.
How can you cut the total cost of a loan?
The steps below work on the traps in the previous section. Each one either reduces the principal, shortens the period over which interest is charged, or removes an avoidable charge. None of them guarantees a particular saving, because the outcome depends on your lender’s terms and your repayment pattern.
- Compare the total amount repayable across lenders. Ask each one for the total of EMIs, fees and charges over the full tenure, and compare those totals side by side rather than the EMI or the headline rate.
- Choose the shortest tenure you can comfortably afford. Use the tenure table above as a guide: a shorter tenure means a higher EMI but less interest in total.
- Decline optional insurance unless you have asked for it and understand what it covers, what it costs and whether the premium is charged once or recurs.
- Check the prepayment and foreclosure charges before you choose a lender. These decide whether a part-payment or a full closure saves you money.
- Make part-payments when you have spare cash, ideally early in the tenure, and ask the lender in writing how a part-payment is applied to the principal.
- Pay the full card balance where you can, and never treat the minimum due as your payment target.
- Keep a buffer for each EMI date so that a short delay does not trigger late or bounce charges.
- Take a new loan only after you have added up the EMIs and charges on the loans you already hold.
If high interest credit card debt is the cost weighing on you most, you can review your options on the BillCut homepage. Compare the full repayment cost, including fees and charges, before you decide on any option.
What should you do if a lender charges more than you agreed?
Check the charge against your loan agreement and the schedule of charges first. If the lender cannot explain it, ask for a written breakdown and keep the reply. A charge you did not agree to is a reason to escalate, not a cost to accept silently.
Start with the lender’s own grievance process. If the issue is not resolved, you can file a complaint through the Reserve Bank of India’s Complaint Management System, which is the route for complaints against regulated entities. If the lender still does not resolve it, the Reserve Bank of India’s Integrated Ombudsman Scheme is an escalation route against a bank or non-banking financial company (NBFC).
Before you borrow, you can check whether a lender is registered on the Reserve Bank of India’s Sachet portal, which also takes reports of illegal lending. For consumer complaints against financial service providers, the National Consumer Helpline can be reached on the toll free number 1915. For plain borrower guidance, the Reserve Bank of India’s own financial education material is a good starting point.
How does BillCut fit into this?
BillCut is a debt refinancing platform, so it is one of the providers in the category this article covers. It is aimed at borrowers who carry high interest credit card debt. The problem it addresses is the one described above: a balance that keeps accruing interest while you make minimum payments, and the cost that builds while you wait.
Refinancing does not remove the costs covered in this article. It changes the loan you repay. Before you consider any refinancing option, you still need the complete picture: the interest method, any processing fee, the tenure, the prepayment rules and the total amount repayable. Compare that total with what you would pay by keeping the current balance and repaying it another way. A lower rate does not always mean a lower total if the tenure is much longer, and an offer can carry its own fees.
Refinancing suits some borrowers better than others. If your card balance is large relative to your income, and you can afford the new EMI with a buffer left over, comparing an offer may be worth your time. If you can clear the balance from savings or regular cash flow, or if you have already missed payments, a different route may suit you better. Read the lender’s schedule of charges in full before you commit to any option.
Who should and who should not act on these steps?
The steps in this article suit most borrowers with an active loan or a loan under consideration. They are a way to read a loan clearly, not a substitute for advice on your own situation.
Who should act on these steps now?
- Anyone with an EMI loan who has not yet checked the interest method, the processing fee or the prepayment and foreclosure charges.
- Anyone paying only the minimum due on a credit card, or carrying a card balance from month to month.
- Anyone about to renew, roll over or take a second loan, who needs the total cost of all loans in one view.
Who should not rely on these steps alone?
- Anyone whose EMIs already exceed their monthly income. Lower cost helps, but the immediate step is to speak with the lender about repayment options and to keep a written record of every conversation.
- Anyone considering a new loan only to repay an existing loan. The fees and charges on both loans must be added together before the decision is made.
- Anyone who has been approached by an unregistered lender or an agent who asks for upfront payment. Check registration first, because a low quoted cost from an unregistered source does not reduce the risk.
Your final check before you sign, prepay or renew
Before you sign, prepay or renew, read the total amount repayable, the processing fee, the prepayment and foreclosure rules, and the late payment schedule. Those four checks cover most of the overpayment traps in this article. Keep a copy of the offer and the schedule of charges, and use them if a charge appears that you did not expect.
Frequently Asked Questions
-
Are there prepayment penalties on loans in India?
Some lenders charge a prepayment charge when you repay part or all of a loan early. The rule for your loan is set out in the lender’s schedule of charges, so check it before you make a part-payment.
-
How can I avoid loan prepayment charges?
Read the prepayment and foreclosure clauses before you sign, and ask the lender in writing whether a part-payment is charged. Where a charge applies, compare it with the interest you would save before you repay early.
-
Do processing fees count as part of the cost of a loan?
Yes. A processing fee is charged upfront and adds to the cost of the loan, even when the interest rate looks low. Compare the fee across lenders as well as the interest rate.
-
Why does most of my EMI go to interest in the early years?
Interest is charged on the balance still outstanding, so early in the loan the balance is high and the interest share of each EMI is high. That share falls as the balance reduces.
-
Is a longer loan tenure always more expensive?
A longer tenure usually lowers the EMI but increases the total interest, because interest is charged for more months. Compare the total amount repayable across tenures before you choose one.
-
Should I pay my loan off early?
That depends on the prepayment or foreclosure charge, the interest rate on the loan and what else the money could do. Compare the interest you would save with any charge, and keep enough cash for emergencies.
-
What is a flat interest rate and why does it matter?
A flat rate charges interest on the original loan amount for the whole tenure. Because the balance falls under reducing balance interest, a flat rate often gives a higher effective cost than the headline rate suggests.
-
Does paying only the minimum due on a credit card cost more?
Yes, if a balance remains. The unpaid balance keeps carrying interest, so the minimum amount is the least you can pay rather than the amount that saves money. Your card issuer’s terms set when interest starts.
-
What happens to my loan if I miss an EMI?
A missed or failed EMI can attract late payment and bounce charges in addition to interest. Under the Reserve Bank of India’s rule on penal charges, a penalty must be a flat penal charge and cannot be compounded into interest.
-
Where can I complain if a lender charges fees I did not agree to?
Start with the lender’s own grievance process. If the issue is not resolved, file a complaint through the Reserve Bank of India’s Complaint Management System, and use the Integrated Ombudsman Scheme as an escalation route against a bank or NBFC.
Are you still struggling with higher rate of interests on your credit card debts? Cut your bills with BillCut Today!